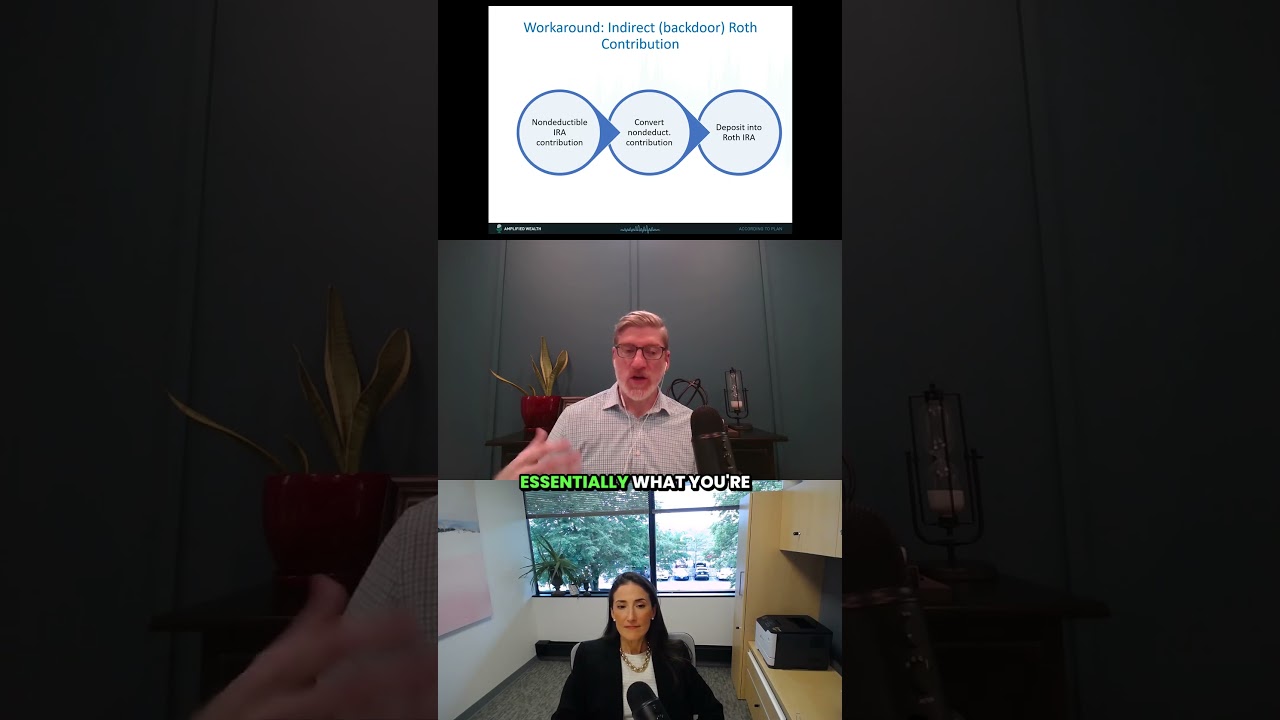
A backdoor Roth IRA is not a loophole - it is a two-step process the IRS has explicitly permitted since Congress removed the income cap on Roth conversions in 2010 (Tax Increase Prevention and Reconciliation Act of 2005, effective tax years starting 2010). Step one: contribute to a Traditional...
A "mega backdoor Roth" is a different and much larger strategy than the standard backdoor Roth IRA, and it only works if your employer's 401(k) plan specifically allows after-tax contributions (beyond the regular pre-tax/Roth deferral) and in-service withdrawals or in-plan Roth conversions. Not...
A backdoor Roth IRA conversion is the second half of the two-part backdoor Roth process, and it's worth understanding on its own. A "conversion" means moving money from a Traditional IRA into a Roth IRA. The IRS taxes the pre-tax portion of whatever you convert as ordinary income in the year of...
Does Your State Tax a Backdoor Roth Conversion the Same Way the IRS Does? Written by Samuel, Certified Public Accountant Published August 2026 Last updated: August 2026 About this guide: This page is reviewed for tax accuracy by a Certified Public Accountant on our team. It reflects independent...
Here is the real, complete sequence, matching IRS guidance rather than a simplified version. First, open or use an existing Traditional IRA and make a nondeductible contribution (2025 limit: $7,000, or $8,000 if 50+). Second, file Form 8606 with your tax return to document that this contribution...